Confirming the valuation date
Your accountant, solicitor or other adviser should identify the purpose and relevant date. A retrospective valuation describes when the value is assessed; capital gains tax, probate and other matters describe why it is needed. These can overlap. We do not assume the same date or valuation basis applies to every instruction.
The property at the valuation date
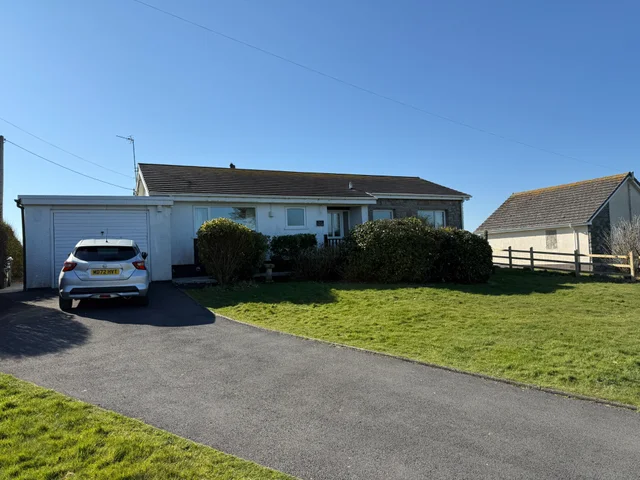
Tell us about extensions, conversions, changes in condition, occupancy or tenure, and when they occurred. Earlier photographs, plans and transaction records may assist. A visit today cannot by itself establish every feature of a home years ago, so the report explains material assumptions and evidential limits.
What your report includes
The agreed report sets out the property, purpose, valuation date, evidence and reasoned opinion of value. Your tax adviser deals with tax liability, reliefs and the treatment of the valuation. We cannot promise that HMRC or another recipient will accept a particular figure without enquiry.
Fees and arrangements
The property’s size and complexity, the age of the valuation date, access, available evidence and intended reporting requirements all affect the work. Send any written request from your adviser, with personal financial information removed where it is not needed for a quotation.